MUMBAI: A study by RBI has found that interest rates adjust upward more completely during a tightening phase than they do downward during an easing phase.According to the study, published in RBI Bulletin, banks passed on 76.4% of the repo rate increase through contract repricing, with lending rates rising by 191 basis points following a 250-basis-point hike between March 2022 and Jan 2025.During the easing phase between Feb 2025 and March 2026, they passed on only 64% of the rate reduction, with lending rates falling by 80 basis points following a 125-basis-point cut. The study, titled ‘Transmission to Lending Rates of SCBs: Price versus Composition Effects in WALR’, notes that changes in the weighted average lending rate (WALR) reflect both changes in lending rates and shifts in loan-book composition.
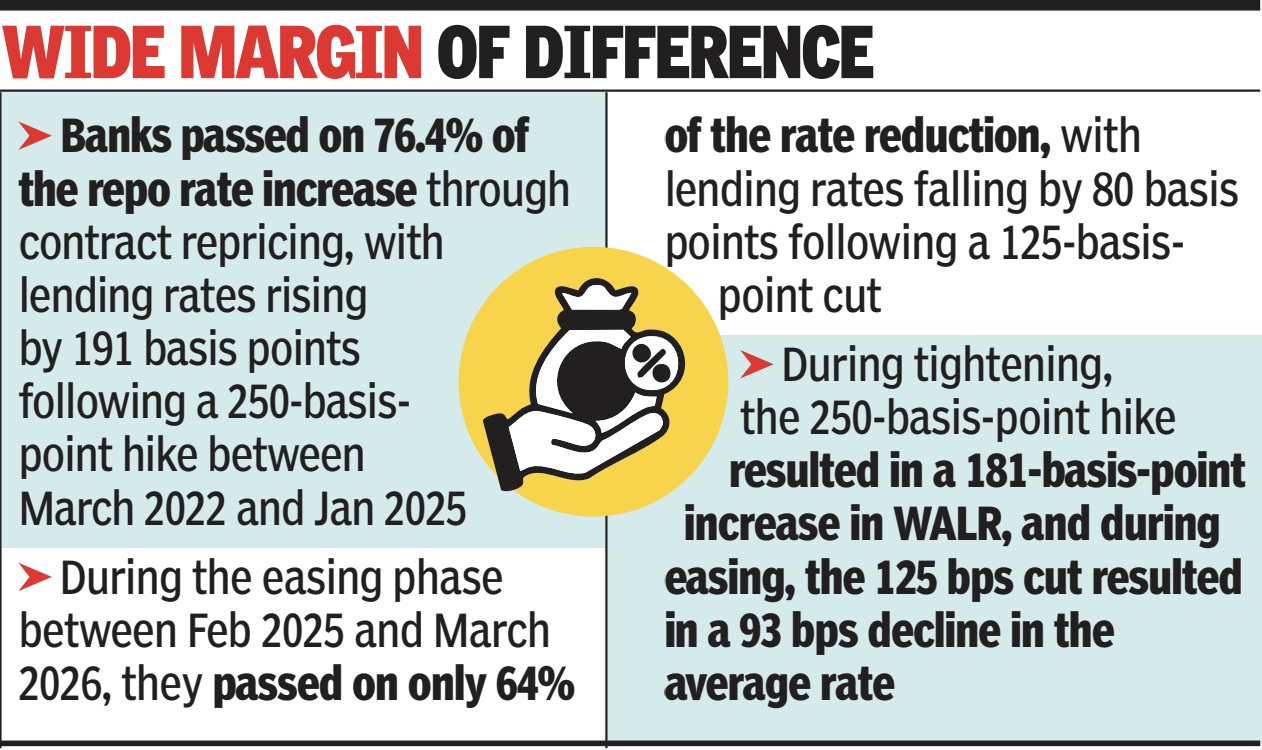
While monetary policy pass-through to contracted loan rates was notably lower during the easing cycle (64%) than in the tightening cycle (76.4%), this gap narrowed significantly when evaluating the headline WALR—which captures shifts in credit composition—narrowing the pass-through disparity to 74.4% in the easing phase compared to 72.4% during tightening. During tightening, the 250-basis-point hike resulted in a 181-basis-point increase in WALR, and during easing, the 125 bps cut resulted in a 93 bps decline in the average rate.During easing cycles, banks protect net interest margins (NIMs) by raising spreads or shifting towards higher-yielding loans, weakening rate-cut transmission. In March 2026, fresh lending rates rose 12 basis points despite the easing stance, according to RBI researchers Yuvraj Kashyap, Kamal Gupta and Arvind Jha.MSME loans had the biggest impact on fresh-loan WALR, with rates falling 122 basis points during the Feb 2025-March 2026 easing cycle, against a 125-basis-point repo cut. For MSMEs, benchmark-linked repricing accounted for 118 basis points, reducing system-wide WALR by 24 basis points, over 2.6 times any other sector’s contribution.Education loan rates fell the most, by 162 basis points, but contributed virtually nothing to the overall WALR decline because of their small share of credit. Rupee export credit rates fell 161 basis points but contributed just five basis points. Large-industry rates fell 67 basis points, contributing nine basis points to the decline; a nine-basis-point positive weight effect, reflecting shifts towards higher-spread loans or lenders, partly offset the pressure.